A trillion-dollar chipmaker, and the quiet risk nobody mentions
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Above the Fold The mood flipped, and chips led the charge What a difference a few days makes. Last Wednesday the market was shaken by the Fed's rate hike and the Dow shed six hundred points. On Monday it closed at a record, with the Nasdaq up 2.3 percent to a new high, carried almost entirely by semiconductor stocks. Chipmaker AMD jumped about ten percent and crossed a trillion dollars in market value; Intel popped twelve percent; Qualcomm added nine. Oil slid and Treasury yields eased at the same time, and just like that, fear turned to greed.  I enjoyed the green Monday the same way I enjoy good weather. I did not rearrange the furniture over it. Two things are worth keeping in mind under the confetti. First, a record built on a handful of chip names is a narrow record; the same index that soars on five stocks can sag on them too. Second, a company worth a trillion dollars is priced for a nearly flawless decade, and paying up for perfection is one of the quieter ways money gets lost. None of that means selling, and none of it means chasing. It means noticing that the market's mood swung hard in four days while the actual economy barely moved. The plan that came through last week's fright and this week's party unchanged is the one that never bet the house on whoever the crowd loves this morning. From Washington A new $6,000 deduction hiding in the tax code One of the friendliest tax changes in years is already live, and a lot of the people it helps have not heard of it. The 2025 tax law created a bonus deduction of up to $6,000 for anyone who is 65 or older, $12,000 for a couple who both qualify. It sits on top of the regular standard deduction and the existing extra amount for older filers, and it works whether a person itemizes or takes the standard deduction. There is fine print, as always. The deduction is in place for tax years 2025 through 2028, and it fades out at higher incomes: for a single filer it starts shrinking once modified income passes $75,000 and is gone by $175,000, and for a couple it runs from $150,000 to $250,000. For a household under those lines, this is a straightforward few hundred to a couple thousand dollars kept, just for being the age it already is, with no special forms or hoops. I have watched too many returns leave money like this on the table simply because no one flagged it. Anyone doing 2026 planning should make sure it gets counted. The IRS lays it out in its filing-season notes for older taxpayers. Money only, no politics.
Tomorrow Today The house that printed itself 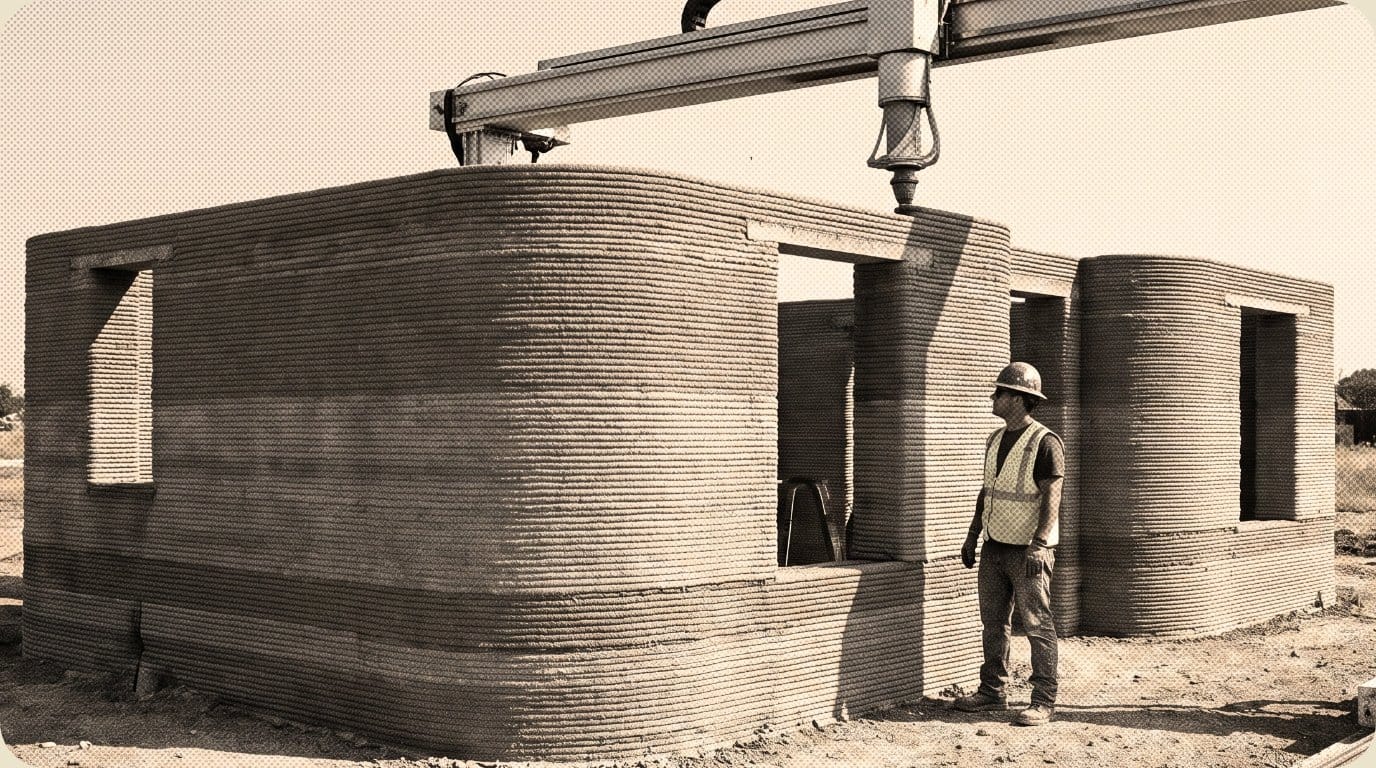 While the chip stocks grabbed the headlines, something quieter is happening in a few American neighborhoods: the houses are being printed. In Houston, a development called Zuri Gardens is rising as eighty fully affordable homes squeezed out of a low-carbon concrete by a giant 3D printer, designed to shrug off floods, fire, and even a tornado. In California, a printer laid the walls of a thousand-square-foot house thirteen feet high in twenty-four days. Some modular versions cost roughly forty thousand dollars to produce. Housing is the biggest line in most household budgets, so anything that genuinely bends the cost of building it is worth watching. I like this one because it goes after the expensive part, the labor and time of framing a house, rather than the trim. The honest caveats hold: these are early projects, most people will not buy a printed home next year, and the little construction-tech stocks always run hotter than the actual concrete. A cheaper way to build is a slow gift, and slow gifts are the ones that tend to last. The Houston project is described at The Architect's Newspaper. The Five Five things worth a minute
The Long View The crowd's favorite is rarely a plan There is a certain magic to a trillion-dollar company. It feels permanent, inevitable, like it was always going to win and always will. I have lived through enough of these to be gently suspicious of that feeling. The most valuable company in the country has changed hands many times in my life, and the list of past champions that were going to rule forever is long and a little sad. A great business and a great investment are not the same thing, because price decides the difference, and a price built on perfection has nowhere pleasant to go if perfection slips. I remember a client, years back, who put nearly everything into the one stock everyone at his shop swore by. It was a fine company. He simply paid too much and bet too big, and it took him a decade to make it back. The lesson stuck with me. You do not have to guess which name leads next. You can own a broad slice of the whole market for almost nothing, let the champions rise and fade inside it, and skip the part where your retirement rides on this morning's darling. Enjoy the record. Just don't marry it. Run the numbers and the story changes. Mind what you keep.
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|