Prime just hit 7% — the debt to pay down first
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Above the Fold The Fed moved, and it wasn't a one-off After months of the whole country guessing, the Federal Reserve raised its benchmark rate on Wednesday, a quarter point, to a range of 3.75 to 4 percent. It is the first increase since 2023, and the vote was unanimous. The bigger news was in the fine print. Fed Chair Kevin Warsh struck a hard line on inflation, saying this summer's readings do not tell him the underlying trend has meaningfully improved, and the committee's own projections show sixteen of eighteen officials expecting at least one more hike before the year is out. Stocks were higher until he spoke, then rolled over; the Dow gave back about six hundred points.  Here is where it reaches a household, and it reaches fast. The prime rate moves in lockstep with the Fed, so it just stepped up to 7 percent, and nearly every credit card and home-equity line is a variable rate built on prime plus a margin. That means the balance you carry gets more expensive inside a statement or two, not someday, and the dot plot says it may happen again before Christmas. I stopped trying to out-guess the Fed a long time ago. It moved and told us more may come, so I act on the fact, not the forecast, and the fact says the costliest variable balances, cards first, are exactly where a dollar of paydown now earns its best return. Savers get the mirror image, safe yields tick up too, but the debt side is the one with a clock on it. From Washington The year-end deadline that carries a 25% penalty For anyone living off a retirement account, a hard date is coming into view. Required minimum distributions, the amount the government makes a person pull out of a traditional IRA or 401(k) each year once they reach 73, must be taken by December 31. Skip it, or come up short, and the penalty is a steep 25 percent of what should have come out, though it drops to 10 percent if the shortfall is fixed within two years. The money angle is not whether to take it, that part is required, but how to take it on your own terms. Every dollar of an RMD lands as ordinary income and can nudge a tax bracket, lift the taxable share of Social Security, or bump a Medicare premium two years out. There is room to be deliberate: give the distribution straight to charity from the IRA and it can satisfy the requirement without adding to income, or spread withdrawals through the year rather than scrambling in late December. First-timers who turned 73 this year get one delay, to April 1, though doubling up next year has its own tax cost. I watched more than one client turn a quiet November into a frantic one over this. The rules sit with the IRS. Money only, no politics.
Tomorrow Today Big Tech goes nuclear to feed the AI machine 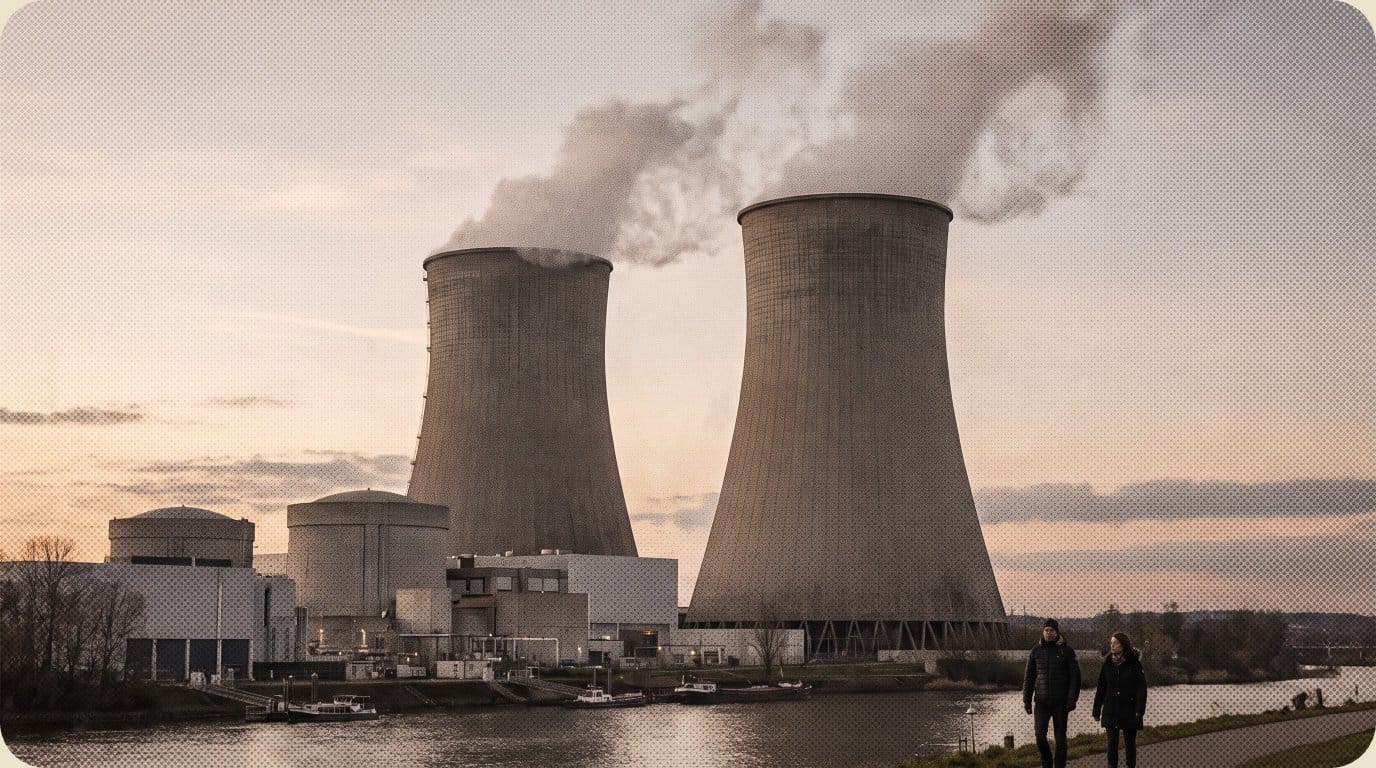 The newest twist in the AI story is not a chatbot, it is a power plant. Data centers are so hungry for electricity that Meta, Amazon, Microsoft and Google have committed tens of billions of dollars to nuclear, from full-size reactors to a wave of small modular ones, to keep their AI running. Meta has backed a 1.2-gigawatt campus in Ohio; Amazon locked up nearly two gigawatts of nuclear supply through 2042. Two things follow for a wallet, and neither is a stock tip. First, all that new demand pulls on the same grid that powers a house, and utilities are already citing data centers when they ask regulators for higher rates, so the AI boom can quietly show up on a light bill. Second, every hot story grows a crop of tiny nuclear stocks priced on press releases, and even nuclear's own experts warn against the PR hype, because a signed power deal is years from a working reactor. I do not buy a company because its field is exciting. I buy it because it makes money, or I leave it alone and just keep an eye on the meter. The Five Five things worth a minute
The Long View Act on the move, not the guess For weeks the only question anyone asked was whether the Fed would go. Now it has gone, and it has said more may follow, and the useful response is not to keep re-arguing the forecast. It is to do the two plain things the move actually calls for. Shrink the debt that just got more expensive. Let the savings that finally pay real interest be paid. Neither one requires knowing what happens at the next meeting. I spent thirty-five years watching people wait for a certainty that never quite arrives, some perfect signal that it was safe to act. The ones who did fine were not the best forecasters. They were the ones who moved on facts as the facts landed, a little at a time, and let the guessing go. A rate went up on Wednesday and may go up again. That is enough to work with. Trim what costs you, lock in what pays you, and let the next meeting be the next meeting's problem. Mind what you keep.
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|