The 10-year just hit a 2007 high — here's the upside for you
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Above the Fold Safe money finally pays like it used to The whole country will watch the Federal Reserve this afternoon, but the number that matters most to a household moved yesterday, quietly and on its own. The 10-year Treasury yield climbed to 5.04 percent on Tuesday, its highest since 2007, nearly two decades. That yield is the anchor under a mortgage and a car loan, so it makes borrowing dearer. It also does something a saver has not seen in a very long time: it pays real money on safe, boring places to park cash.  For fifteen years, a savings account and a certificate of deposit paid close to nothing, and cash on the sidelines quietly lost ground to inflation. That has flipped. Short Treasuries, CDs, and money-market funds now pay in the fours and low fives, real income on money that carries little risk. I waited a long time for safe money to be worth holding, and when it finally is, I lock some of it in rather than leave it idle in a checking account earning a rounding error. Rates this high do not last forever. The Fed may talk this afternoon about where they go next, but the chance to capture this income is sitting on the table right now. From Washington The Medicare letter in this month's mail decides next year's bill A plain envelope is landing in mailboxes right now that quietly sets a lot of household budgets for next year. Every Medicare Advantage and Part D plan has to mail its Annual Notice of Change by September 30, and it lays out exactly how the plan shifts for 2027: the premium, the deductible, the copays, which drugs are covered and on what tier, and which doctors stay in the network. The trap is that doing nothing renews the plan automatically, every change included. A drug can jump to a higher tier, a familiar doctor can fall out of network, a premium can climb, and the only warning is that letter. It pays to read three things: whether the monthly premium rose, whether a regular prescription got dropped or bumped up a tier, and whether a doctor left the plan. Then compare, because Open Enrollment runs October 15 to December 7, and any switch takes effect January 1. I watched more than one person keep a plan that had quietly stopped covering their medicine, simply because the letter went in a drawer. Money only, no politics.
Tomorrow Today Quantum computers get real, and so does the hype 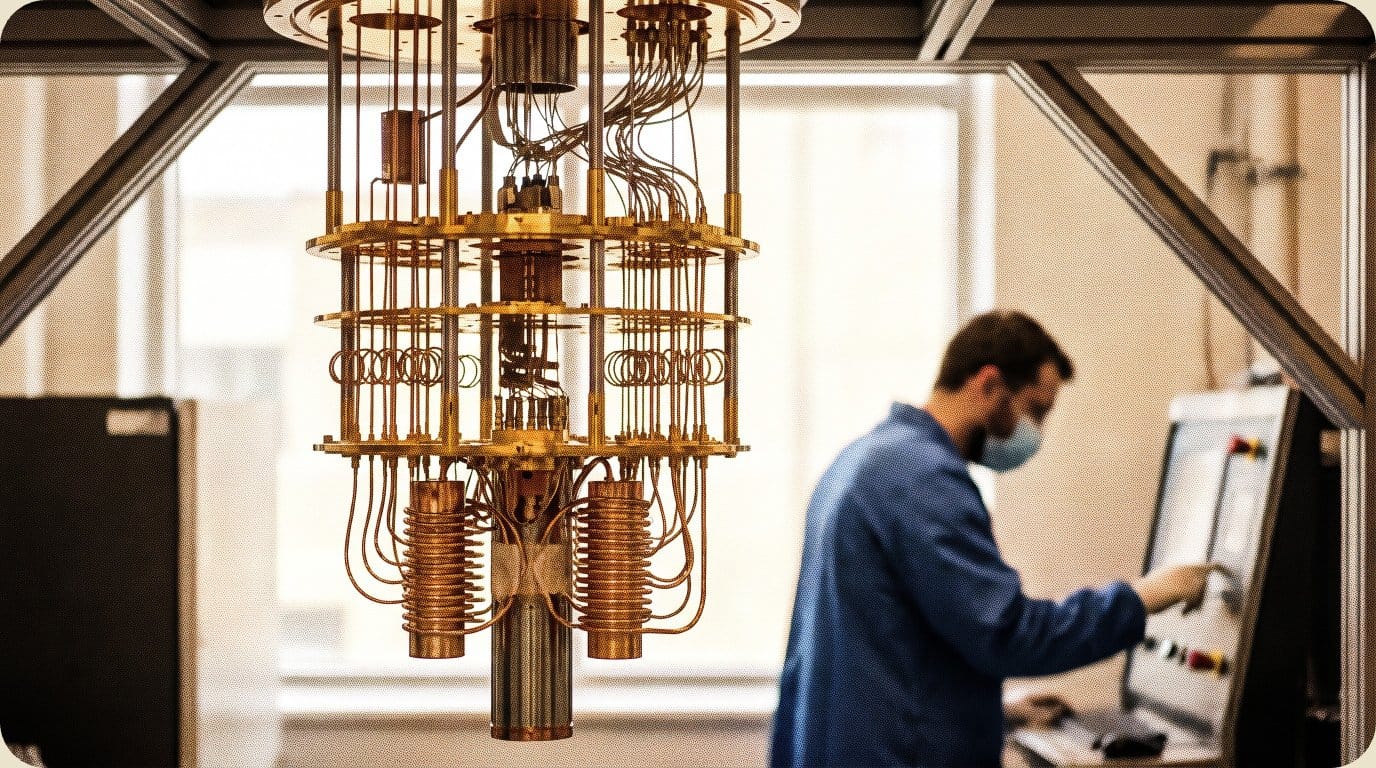 Quantum computing had a genuine year. Error-corrected machines are reaching their first customers, and researchers are starting to show the technology beating ordinary computers at a few narrow tasks. Even the believers are waving a caution flag: the head of quantum hardware at Amazon called the field full of a tremendous amount of hype, hard to separate from the parts that are real. Here is where it touches a wallet, and it has nothing to do with physics. Whenever a science story runs hot, a crop of tiny quantum stocks runs hotter, priced on a promise that is still years from a product. A breakthrough in a lab is not a business with customers and earnings, and the two can drift apart for a long time. I do not buy a stock because its field is exciting. I buy it because it makes money, or I leave it alone. Watch quantum for the wonder of it. Keep the speculation money small enough that being wrong is a shrug, not a wound. The Five Five things worth a minute
The Long View Getting paid to be patient It is a strange thing to say after fifteen years of near-zero rates, but safe money is finally worth holding again. The same climb in yields that makes a new mortgage sting is handing anyone with cash a real return on it, four and five percent on things that do not keep a person up at night. The whole room is staring at the Fed this afternoon. The opportunity is sitting quietly on the other side of the table. I spent thirty-five years watching people chase the exciting money and ignore the boring kind, and the boring kind is the part that pays the bills in retirement. When safe income is this good, the discipline is not to reach for more, it is to lock some of it in before it fades, a ladder of CDs or short Treasuries that keeps paying whatever the Fed decides at two o'clock. The stock market will do what it does. A dependable stream of interest, captured while the capturing is good, is the quieter win. Rates this high are a gift with an expiration date. Mind what you keep.
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|