There's a tax line on your Social Security that hasn't moved since 1984.
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Above the Fold The rate that runs your loans is climbing again The first trading day of September, and the story was not in the stock indexes, which barely moved. It was in the bond market. The 10-year Treasury yield rose to 4.76 percent on Monday, its highest since early last year and the fourth straight session higher.  The push came from oil. Over the weekend U.S. forces struck targets near the Strait of Hormuz and Iran struck back, and crude jumped about 1.5 percent to near $87 a barrel, reviving inflation worries just as the Fed's new chair has turned hawkish. Here is why a bond yield belongs on your kitchen table: the Fed sets the overnight rate, but your mortgage, your car loan, and the government's own interest bill take their cue from the long end of the bond market. That long end keeps climbing while the Fed sits still. I have watched people wait years for the Fed to cut while the rate that actually priced their loan drifted the other way. From Washington A tax line that hasn't moved since the 1980s A quiet corner of the tax code is worth knowing this month. Social Security benefits start getting taxed once your combined income tops $25,000 for a single filer or $32,000 for a couple. Those lines were written into law in 1984, and they have never been adjusted for inflation. Prices have more than tripled since; the thresholds have not moved a dollar. The result is a slow squeeze. Every cost-of-living raise, including this year's 2.8 percent, nudges a few more people past a line that stopped rising four decades ago, so a larger slice of benefits becomes taxable. September also happens to be the last of the three months of inflation data that set next year's raise. The way I see it, this is a what-you-keep problem worth a little planning: it pays to know your own combined-income number before you pull from an IRA in December, because a small withdrawal can cost more than its size if it trips the line. Money only, no party in it.
Tomorrow Today Apple's next phones, and the price you actually pay 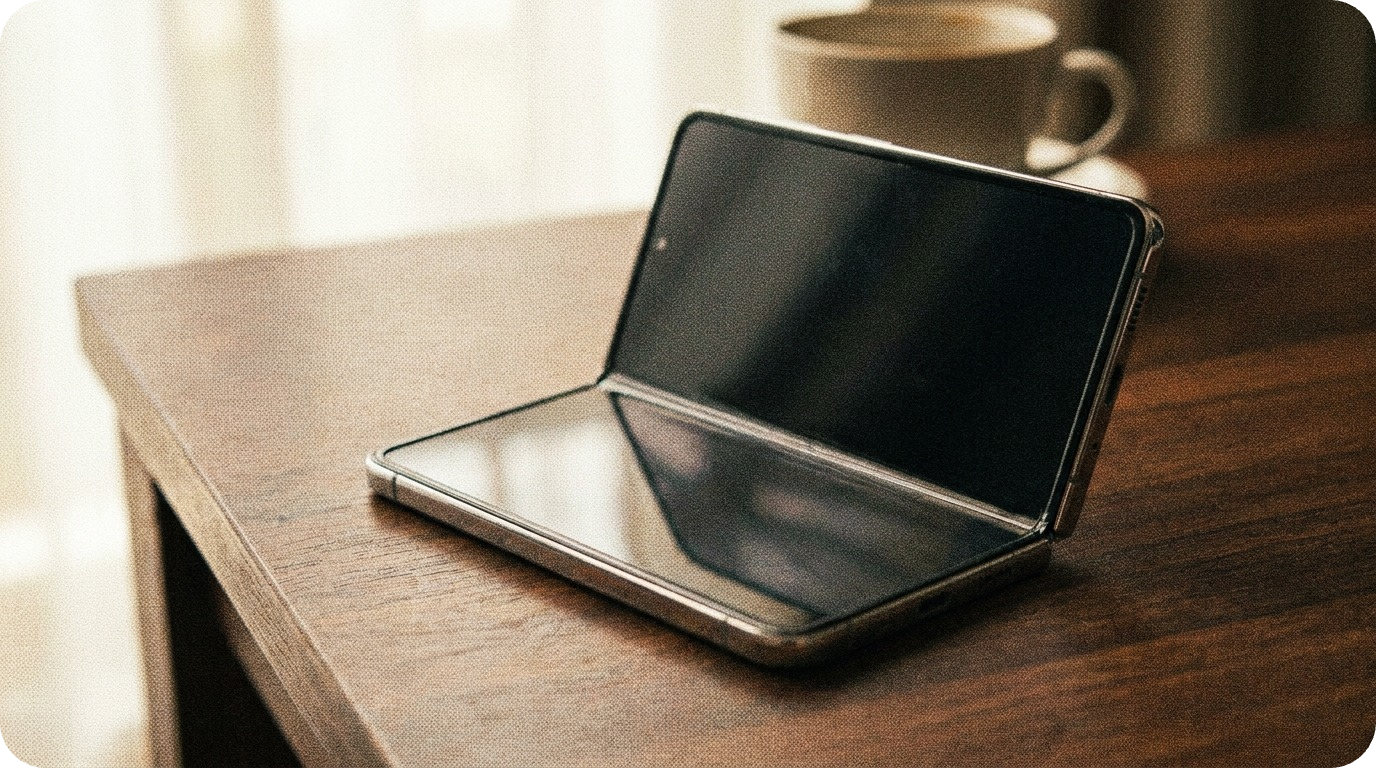 Apple has set an event for September 9, its yearly iPhone launch, and this one carries more than the usual refresh. Alongside the iPhone 18 Pro line, the company is expected to show its first folding phone, rumored to be called the iPhone Ultra, plus a new Apple Watch. A phone that unfolds into a small tablet is a real step, and it will draw a crowd. It will also carry a top-tier price, and a first-generation folding screen is exactly the sort of thing that gets better and cheaper in year two. The wallet move on launch day is usually the dull one: check what your carrier gives you for a trade-in, and ask whether the phone in your pocket has another year left in it. I have never once regretted keeping a working phone one more cycle. New is exciting. Paid-off is better. The Five Five things worth a minute
The Long View The rate nobody puts on a podium Two forces pushed the same way to open September: oil up on the Middle East, and long-term interest rates up right alongside it. The Fed has held its rate since July, yet the 10-year and 30-year yields keep climbing, and those are the numbers that quietly set what a mortgage or a car loan costs. I spent thirty-five years watching people track the Fed's headline rate like a scoreboard while the rate that actually priced their loan lived somewhere they never looked, in the bond market. September tends to be a jumpy month for stocks, and this one opens with a jobs report on Friday and a Fed meeting two weeks out. None of it is worth rearranging a plan over. Keep the cushion, keep a payment you can carry, and let the noise stay noise. Labor Day comes next Monday, a good day to do nothing with the market at all. Mind what you keep.
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|