There's an argument inside the Fed, and today we get to read it.
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Above the Fold Today the Fed lets us read the argument This afternoon at two o'clock Eastern the Federal Reserve publishes the minutes of its last meeting, the one on September 16 where Kevin Warsh and the committee lifted the target rate to a range of 3.75 to 4.00 percent. The decision is already known. What the minutes add is the room behind it: how many officials wanted to push rates higher still, how many wanted to stop, and how uneasy they were about the whole thing. That split is what traders will comb the pages for before the afternoon is out.  None of this changes your mortgage rate today. The minutes are three weeks old and the committee does not meet again for a while. But they are the clearest signal we get of whether the cost of borrowing is likely to climb further or settle where it is, and that question reaches every loan a household carries and every dollar a saver has parked. I read minutes for the disagreement more than the decision. A unanimous vote tells you little. An argument tells you where the next move might come from, and how close the Fed is to being done. From Washington A new deduction worth up to $6,000 for older filers The tax law passed last year carved out something that is easy to miss on a return. Starting with 2025, a taxpayer who reaches 65 by the last day of the year can claim an extra $6,000 per person, on top of the standard deduction and the older existing add-on, and it runs through tax year 2028. A married couple where both have turned 65 can take it twice. It counts whether you itemize or not. A deduction like this works by shrinking the income the government gets to tax, so it can quietly pull a withdrawal down into a lower bracket, which is where it earns its keep. The catch is that it fades as income rises, thinning out above $75,000 for a single filer and $150,000 for a couple, and disappearing entirely well above that. I spent years watching people leave a break like this sitting on the table because no one told them it existed. It is worth pricing in before year-end, because it can change what an extra IRA withdrawal or a Roth conversion actually costs you. Money only, no politics.
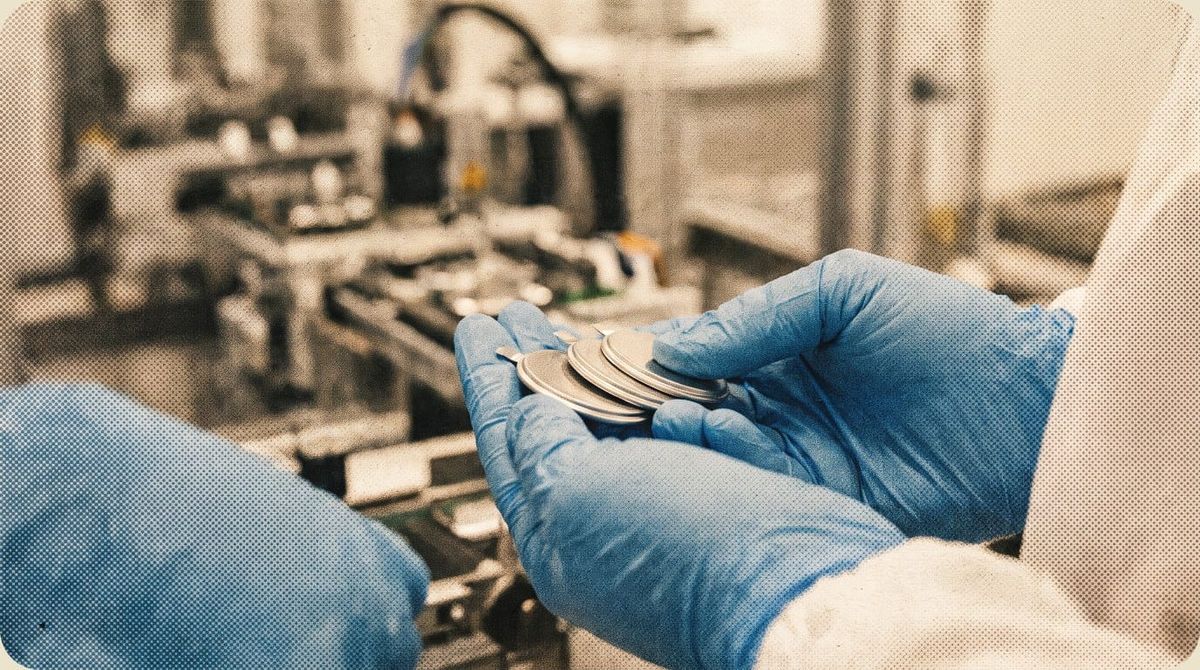
Tomorrow Today The battery that could reshape the car, inching off the bench  The battery inside almost every electric car today is lithium-ion, good but near the limits of what it can do. The next step, a solid-state cell, has been promised for years. This year it got closer to real. QuantumScape fired up a highly automated pilot line in San Jose, California, and is shipping sample cells to carmakers to test. The cells hold more energy than today's batteries and charge from 10 to 80 percent in under fifteen minutes, and a version already powered a Ducati electric motorcycle in a public demonstration run with Volkswagen's battery arm. A cheaper, longer-lasting, faster-charging battery would eventually mean cheaper electric cars and cheaper storage for the power grid, the kind of thing that bends an electric bill over a decade. That is the promise. The sober part is that the hard part is still scaling from a pilot line to millions of identical cells, a jump that has humbled every battery maker that tried it. No solid-state car is on sale, the public companies in this corner trade on hope and lurch on a single announcement. I admire the engineering and keep any bet on it small enough to shrug off. The Five Five things worth a minute
The Long View You don't have to win the Fed's argument This afternoon a lot of clever people will spend the evening parsing the Fed's minutes, line by line, for who wanted to raise rates further and who wanted to wait. It is worth reading. It is not worth losing an evening of sleep over, and it is certainly not worth trading on. The thing I came to believe slowly, over thirty-five years of other people's tax returns, is that you do not have to settle the experts' disagreement to run your own money well. The committee can stay split for months while your own plan stays plain. Keep some cash you can reach without selling anything. Keep your fixed costs low enough that a higher-for-longer world cannot corner you. Let the rate on money be whatever it turns out to be. The clients who slept best were never the ones who guessed the Fed right. They were the ones whose month worked whether the Fed moved or not. The argument downtown will go on long after today's headlines. Yours does not have to. Mind what you keep.
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|


