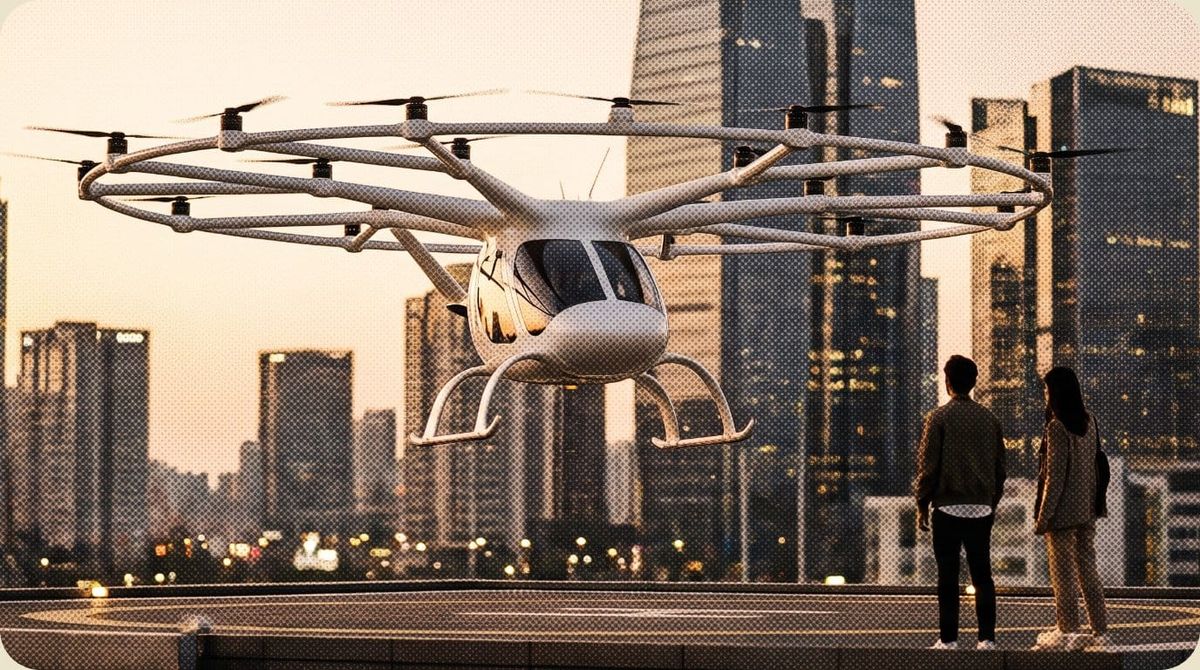
Would you take a 7-minute air taxi over the bridge?
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Above the Fold When good news makes the market frown Thursday handed Wall Street a batch of genuinely good economic news, and the market sulked about it. New claims for unemployment fell to 197,000, a very low number, and the government revised second-quarter growth upward on the back of stronger consumer spending, a picture of an economy holding its ground despite steep interest rates. Stocks fell anyway. The S&P 500 dropped 0.8 percent and the Nasdaq slid 1.1 percent as Nvidia stumbled, the 10-year Treasury yield pushed to a fresh high above 5 percent, and a New York Fed official said out loud that another rate hike by year-end looks reasonable.  This is the strange arithmetic of a rate-worried market: a sturdy economy now reads as bad, because strength keeps the Fed leaning hawkish and keeps money expensive. I understand the logic and I refuse to adopt the mood. A strong job market and a growing economy are good for the people who live inside them, the paycheck, the raise, the customer who can still afford your work, even on the days a trader frowns at the same numbers. Today brings the PCE report, the inflation gauge the Fed watches most, and it lands after this goes out, so I will not pretend to know it. What I do know is that the market's discomfort is a Wall Street feeling, and it does not have to be yours. Keep the plan pointed at the real economy, not at the ticker's mood swings. From Washington The 0% tax bracket that hides in plain sight Buried in the tax code is a rate almost nobody believes is real: zero. For 2026, a married couple filing jointly with taxable income up to $98,900 pays no federal tax at all on long-term capital gains, the profit on investments held more than a year. For a single filer the line is $49,450. And because that is taxable income, figured after the standard deduction, which is larger for those past 65, the gross income underneath can run quite a bit higher and still qualify. Here is why it matters for anyone with a low-income year, and early retirement is often exactly that. A person can sell appreciated stock or fund shares, fill the space up to that threshold, and owe nothing in federal tax on the gain, then buy the same investment back at a higher cost basis, quietly resetting the tax meter for later. It takes a little arithmetic and an eye on the line, because a dollar of gain over the threshold gets taxed at 15 percent, but done with care it is one of the cleanest legal ways to move money off the taxable pile. I ran this play for clients more times than I can count, usually in the calm years between leaving a job and starting Social Security. The rules live at the IRS. Money only, no politics.
Tomorrow Today The taxi is about to leave the ground 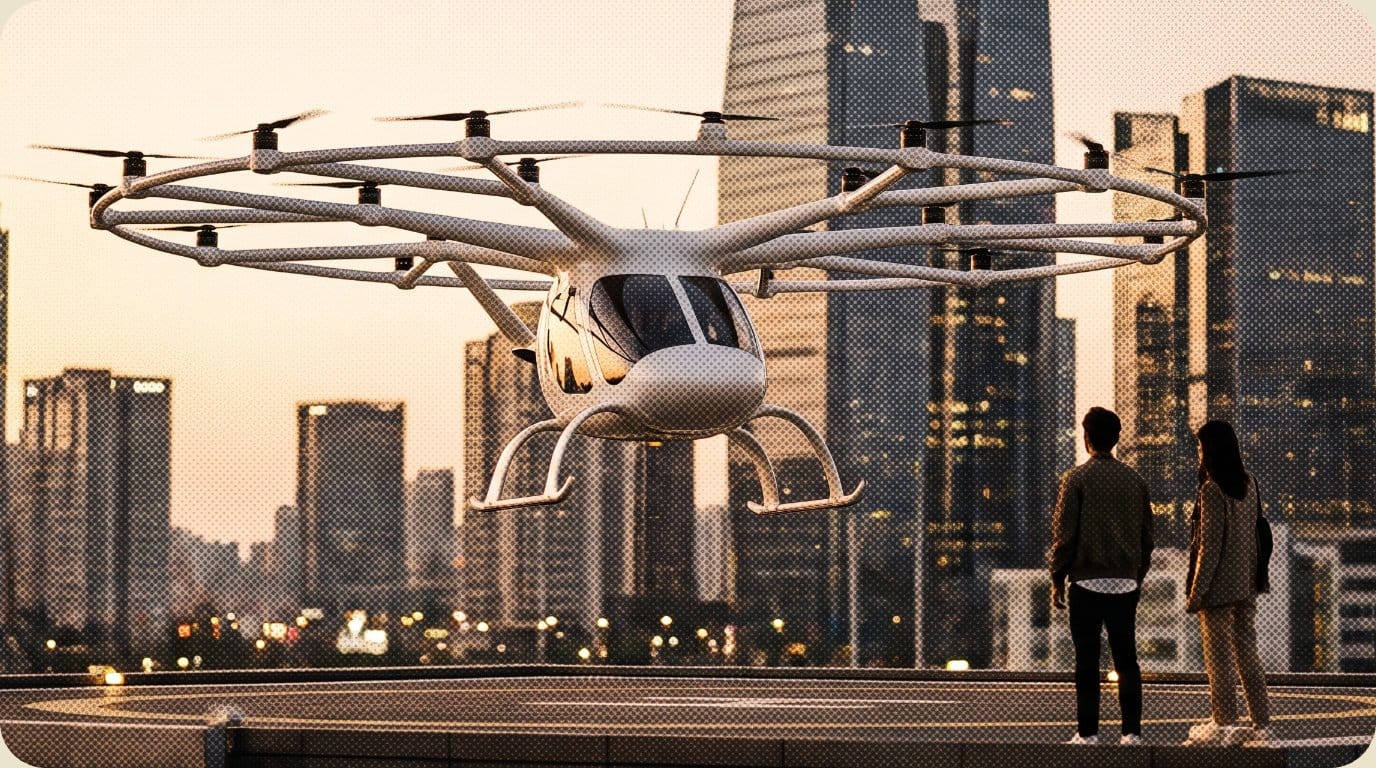 The flying taxi spent a decade as a punchline, and this year it is becoming a schedule. Joby Aviation, partnered with Delta, and Archer Aviation are both aiming to fly paying passengers in electric aircraft that take off straight up, no runway, before the year is out. Joby has reached the fourth of the FAA's five certification stages, the first company to get there, and a federal pilot program is clearing pre-approved aircraft to operate across 26 states. One of Joby's craft already hopped from JFK airport to a Manhattan heliport in about seven minutes. A quiet electric aircraft that skips the traffic is a genuine wonder, and I hope it works. The money lesson is the same one every thrilling new industry teaches. These companies have burned through billions of dollars and years of promises, their stocks lurch violently on every FAA headline, and a seven-minute demonstration flight is not the same thing as a profitable business carrying millions of people. Watch it for the marvel. If any speculation money goes near it, keep the amount small enough that being wrong is a story, not a wound. The rollout is covered by Fortune. The Five Five things worth a minute
The Long View Cheer the economy, not the ticker It was a week that ended on a contradiction worth sitting with. The economy turned in a good report card, low layoffs, solid growth, a consumer still spending, and the stock market marked it down. That happens because a market priced for cheaper money hates being told the money will stay expensive. It is a real feeling on a trading desk. It is not a verdict on your life. I spent thirty-five years watching people get the mood exactly backwards, cheering a frothy market that was quietly setting them up to overpay, and panicking on a red day when the underlying news was actually fine. The tape and the economy are not the same animal. One is a running tally of what a nervous crowd will pay this afternoon; the other is whether people are working, earning, and buying, which is what actually funds a retirement. When those two disagree, I side with the economy and let the ticker have its tantrum. A plan built on paychecks, low debt, and a cash cushion does not need the market to be in a good mood to keep working. The fine print is where your money actually lives. Mind what you keep.
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|